The Question I Am Asked Most Often, and Why It Is the Wrong One
Almost every week, a client asks me some version of the same question: "Which AI stock should I own?"
I understand the impulse. It is the question the financial press has trained everyone to ask. But after two decades of building cross-border portfolios, I have come to believe it is close to useless. Asking which AI stock to own in 2026 is like asking, in 1996, which internet stock to own. The honest answer then was that the internet would create enormous value while destroying most of the companies that first claimed to represent it. I expect the same to be true here.
The better question, the one I now put to clients before I put anything into a portfolio, is this: which layer of the intelligence economy do you actually want to be paid by, and what is the contractual mechanism by which that payment reaches you?
That reframing changes everything. It moves the conversation away from narrative and toward cash flow, duration, and pricing power. It is also the only framing I have found that survives a capital expenditure cycle turning.
The Intelligence Economy Is a Stack, Not a Sector
When I map this out for clients, I draw a stack rather than a list. Each layer has its own economics, its own competitive structure, and its own relationship to risk.
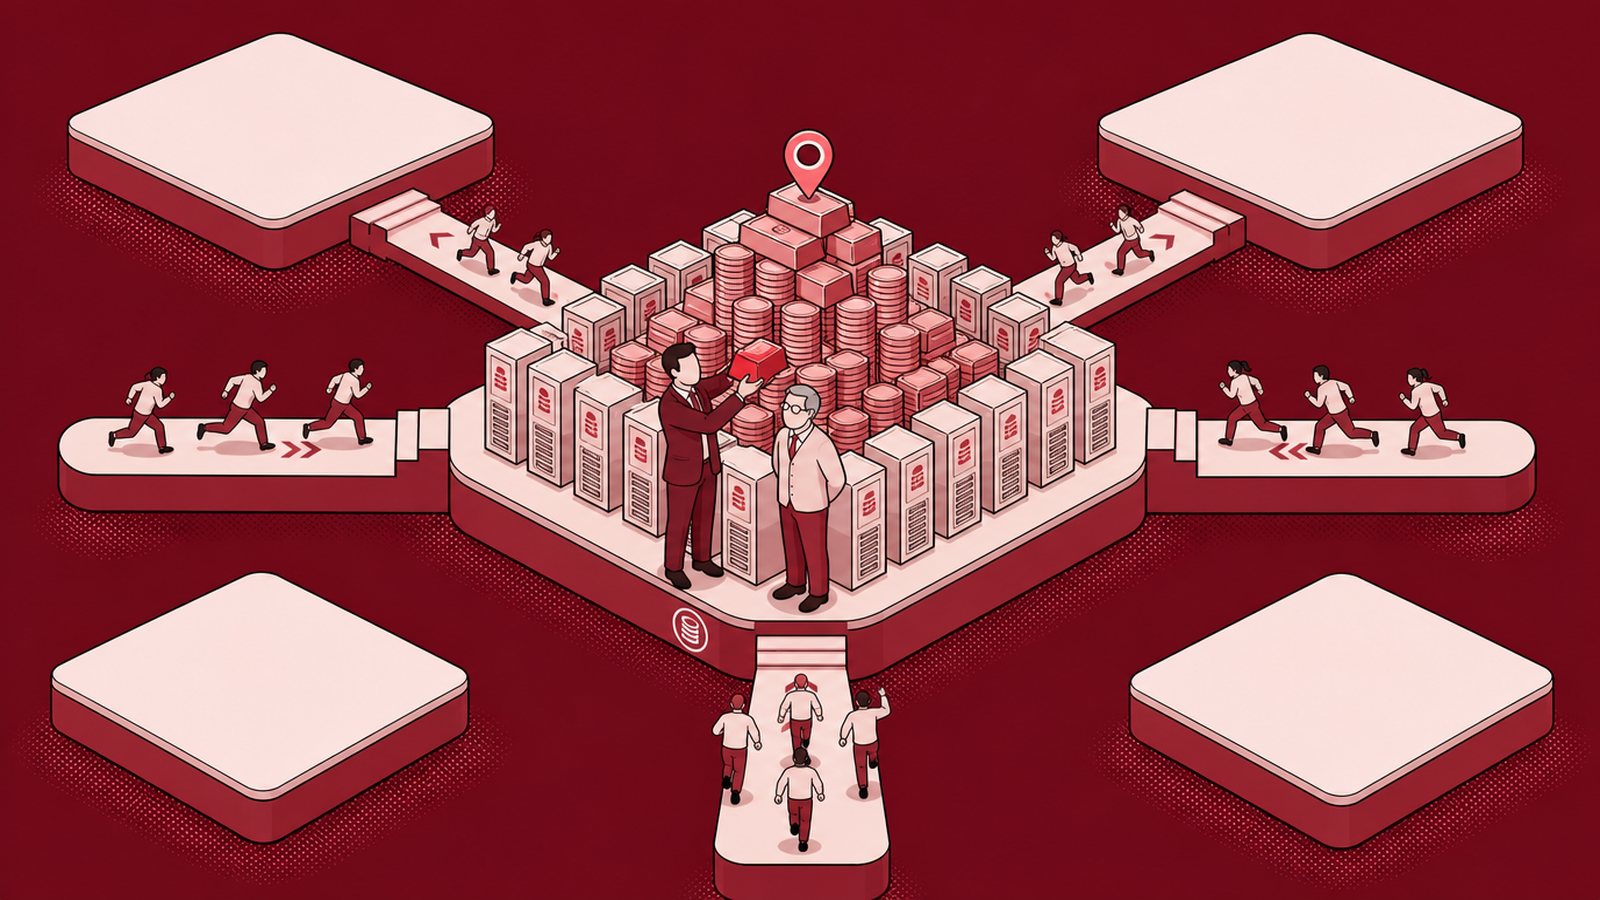
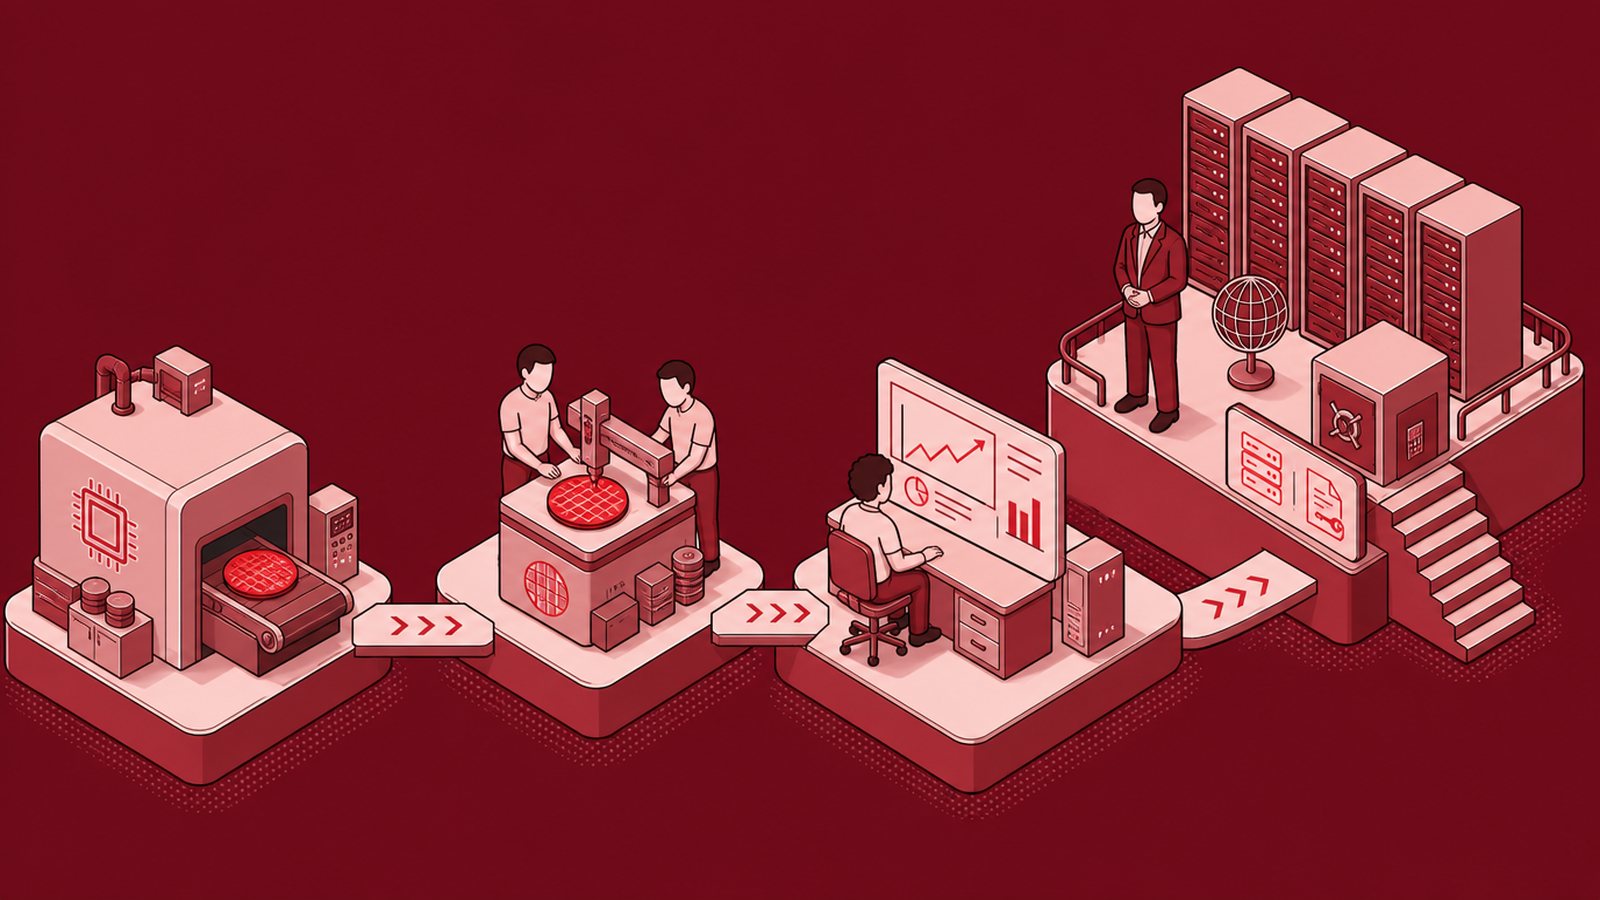
At the base sits energy: generation capacity, grid interconnection, transmission, and increasingly the nuclear and gas assets being contracted directly by hyperscalers. Above that sits land and shell: the physical buildings, the water rights, the permits. Above that, electrical and thermal equipment: transformers, switchgear, uninterruptible power supplies, and the liquid cooling systems that dense AI racks now require. Above that, silicon: logic, memory, networking, and the advanced packaging that binds them. Above that, the operating layer: colocation, interconnection, and the real estate investment trusts that own and lease the facilities. And only at the very top sit models and applications, the part of the stack that generates almost all of the headlines and, so far, the least reliable margins.
Most retail portfolios are concentrated at the top of that stack. Most durable cash flow sits nearer the bottom. That mismatch is the central problem I try to solve for clients.
The Scale of the Build, and Why It Matters for Duration
The numbers involved have moved beyond anything the technology sector has previously attempted. Goldman Sachs has projected total hyperscaler capital expenditure from 2025 through 2027 at roughly $1.15 trillion, which is more than double the approximately $477 billion spent across 2022 to 2024. United States data center construction reached a monthly run rate of about $45.1 billion by December 2025, up roughly 85 percent from two years earlier. The International Energy Agency projects global data center electricity consumption will more than double by 2030, approaching 945 terawatt hours.
I cite these figures not to impress but to make a specific point about duration. A spending programme of this size does not switch off cleanly. It is embedded in multi-year construction contracts, in grid interconnection queues that stretch out five to seven years, and in leases with terms of five to fifteen years. That is what an investor should actually care about: not whether the enthusiasm continues, but how long the contracted obligations run after the enthusiasm fades.
This is also why I treat the physical layer differently from the model layer. A large language model can be commoditised within eighteen months. A signed fifteen year lease on a powered shell in a constrained grid region cannot.
The Silicon Layer: Extraordinary Economics, Extraordinary Concentration
I want to be direct about semiconductors, because this is where I see the least honest analysis.
The economics at the leading edge are genuinely exceptional. Nvidia holds something close to 90 percent of the data center graphics processing unit market, supported by a software ecosystem that functions as a switching cost. Broadcom controls roughly 70 percent of the market for application specific integrated circuits and reported AI semiconductor revenue growth of 143 percent year over year in a recent quarter. These are not ordinary businesses.
But the geography of production is a risk that most portfolios simply do not price. Taiwan, through TSMC, still manufactures well over 90 percent of the world's most advanced logic chips. South Korea, through SK Hynix and Samsung, dominates high bandwidth memory. TSMC's Arizona development, a commitment reported at around $165 billion, aims at 2 nanometre volume production by 2030 and, when complete, is expected to supply roughly 30 percent of the company's most advanced output. The European Chips Act targets lifting the European Union's share of global production from under 10 percent to 20 percent by 2030, mobilising over 43 billion euros.
Read those figures carefully. Every serious diversification programme currently underway resolves the concentration problem sometime after 2028, and only partially. Advanced packaging, the step where chiplets are assembled into finished products, remains even more concentrated than fabrication.
Semiconductor lead times reached roughly 40 weeks by March 2026, with memory and fibre optic components among the most constrained. That is not a demand signal alone. It is a fragility signal.
My position for clients is therefore straightforward. I am willing to hold leading edge semiconductor exposure, but I size it as a volatile, geopolitically exposed, cyclical position, not as a core holding. And I insist that clients understand the difference between a company earning economic rent (Nvidia today) and a company earning a cyclical margin peak (much of the rest of the supply chain).
The Physical Layer: Where I Actually Prefer to Sit
Data center real estate investment trusts have delivered results that most investors have not noticed, largely because the category is unglamorous. Over the twelve months ending 20 April 2026, Digital Realty, Equinix and Iron Mountain produced total returns of roughly 38.99 percent, 40.97 percent and 45.05 percent respectively, outperforming the broader REIT sector during a period when conventional real estate struggled with elevated rates.
The reason I favour this layer is structural rather than momentum driven. Three characteristics matter.
First, contracted revenue. Hyperscaler leases commonly run five to fifteen years, frequently with contractual escalators. That converts a technology theme into something closer to an inflation linked bond with equity upside.
Second, power as a moat. In constrained markets, the binding scarcity is no longer land or capital. It is grid access. An operator holding secured interconnection in a supply constrained metro owns something a competitor cannot replicate simply by spending more.
Third, the shift from training to inference. Industry forecasts increasingly point to inference workloads growing faster than training by the end of this decade. Training demand is lumpy and project driven. Inference demand is continuous, latency sensitive, and geographically distributed. Assets serving inference should, in my judgement, carry a longer and steadier revenue tail.
I would add one caution that too few advisers voice. Heavy capital expenditure by REITs suppresses near term distributable cash flow, and retrofitting older facilities for liquid cooling is expensive. Investors buying these names for immediate yield will be disappointed. Investors buying them for a decade of contracted, escalating rent on scarce, power connected real estate are, I think, buying something quite different.
Emerging Market Digital Infrastructure Deserves Separate Consideration
Because mature hubs in the United States, Europe and East Asia are hitting limits on grid capacity, permitting and land, capital is migrating. Querétaro in Mexico saw inventory surge by roughly 450 percent year over year in a single recent quarter. São Paulo remains Latin America's anchor market, reinforced by continuing subsea cable investment. India and the Southeast Asian cluster of Indonesia, Vietnam and Thailand continue to expand on the back of domestic demand and government incentives.
For globally minded investors, particularly those in the Gulf and South Asia whom I advise most frequently, this is a genuine opportunity to invest close to home in an asset class that has, until recently, been available only through United States listed vehicles. I treat it as a distinct allocation with its own currency, regulatory and offtake risks rather than folding it into a generic technology sleeve.
How I Actually Construct the Allocation
I will describe my working framework, with the usual caveat that individual circumstances must govern any real decision.
I think of intelligence economy exposure as occupying between 8 and 15 percent of a growth oriented global portfolio, and I split it deliberately across the stack rather than concentrating it at the top.
Roughly a third to the physical and contracted layer: data center REITs, digital infrastructure funds, and where accessible, private or listed operators in emerging markets. This is the ballast.
Roughly a third to the enabling equipment and energy layer: thermal management, electrical infrastructure, grid and generation assets serving data center load. These businesses often carry order books rather than narratives, which I find reassuring.
Roughly a quarter to the silicon layer, sized in full awareness of its cyclicality and concentration, and rebalanced with discipline rather than conviction.
The remainder, and only the remainder, to model and application exposure, treated frankly as venture style risk within a public portfolio.
Three Questions Before I Commit Capital
I ask the same three questions of every position in this theme.
Who is the counterparty, and how concentrated is it? A supplier deriving most of its revenue from three hyperscalers is not diversified simply because it is listed. Customer concentration is the risk that most reliably converts a growth story into a value trap.
What is the depreciation schedule, and is it honest? Extending the assumed useful life of computing hardware flatters earnings today and creates a reckoning later. I read the footnotes on this before I read the growth commentary.
Is this asset inside the approved deployment path? In dense AI environments, operators cannot casually substitute untested cooling architectures or lower grade electrical components. Being a qualified, specified supplier is a far more durable position than being a technically superior one.
The Bear Case I Take Seriously
I distrust any thesis whose advocates cannot state the opposing case properly, so let me state mine.
The first concern is circularity of financing. A meaningful portion of demand in this ecosystem is being funded by capital that flows between the same small group of participants: chip vendors investing in model developers, model developers committing to cloud capacity, cloud providers purchasing chips. Each transaction is legitimate. In aggregate, the pattern resembles vendor financing, and vendor financing has a poor historical record of surviving a funding tightening.
The second is the return on invested capital question. Over a trillion dollars of capital expenditure must eventually be serviced by revenue from applications that end customers voluntarily pay for. That revenue is growing quickly, but it does not yet reconcile to the scale of the build. The gap may close. It may also close by the build slowing rather than the revenue accelerating.
The third is depreciation honesty, which I mentioned above and repeat because it is the single most consequential accounting judgement in the sector. If the economic life of AI accelerators proves shorter than the reported useful life, current earnings across the ecosystem are overstated, and the correction will arrive suddenly rather than gradually.
None of this changes my structural conclusion. It changes where in the stack I am willing to hold concentrated positions, and it explains why I weight toward assets with contracted duration rather than assets with narrative momentum.
What I Tell Clients in Closing
The intelligence economy is real, and it is being financed on a scale that will outlast the current enthusiasm. But the returns will not be distributed evenly across the stack, and they will not accrue primarily to the companies with the most recognisable names.
My conviction is that the most reliable long term returns in this theme will be earned by the owners of scarce physical assets sitting under the intelligence layer: the power, the land, the interconnection, and the buildings. That is an unfashionable conclusion. It is also, in my experience, how infrastructure booms have always eventually paid their investors.
The gold rush made a small number of prospectors wealthy. It made a far larger number of suppliers, landowners and railway operators wealthy with considerably less variance. I would rather my clients own the railway.
Sources and further reading (12)
- Goldman Sachs hyperscaler capex projections and AI data center component supply analysis, Accuris
- Data center REIT total returns and AI infrastructure investment guide, Angel Investors Network
- Best data center stocks, ETFs and REITs, U.S. News
- The AI data center stock boom and how to invest, Forbes
- Investing in AI data center infrastructure 2026, training versus inference, Commons LLC
- Why DLR and EQIX are the best data center REITs for the AI boom, MarketWise
- TSMC Taiwan geopolitical risk, concentration and resilience planning, Mapshock
- TSMC, CHIPS Act and semiconductor geographic concentration, EnkiAI
- Chips, power and geopolitics, Microwave Journal
- Powering data centers in emerging markets, Atlantic Council
- Global data center trends 2026, CBRE
- AI infrastructure stocks and ETF exposure routes, Trade The Pool