The Most Expensive Mistake in Modern Value Investing
I want to begin with an admission, because I think it is more useful than a thesis.
For a period of my career I applied a disciplined value framework to companies it was not built to assess. I looked at price to book ratios, at price to sales multiples, at tangible asset backing, and I concluded that a certain category of business was persistently, obviously overvalued. I was rigorous. I was consistent. I was wrong for a decade.
The failure was not one of discipline. It was that my toolkit had been designed for businesses whose value resided in things that could be counted, and I was applying it to businesses whose value resided in relationships between users. Those relationships appear nowhere on a balance sheet.
Understanding why that happens, and what to use instead, is in my view the single most important analytical upgrade available to a global investor today.
What a Network Effect Actually Is
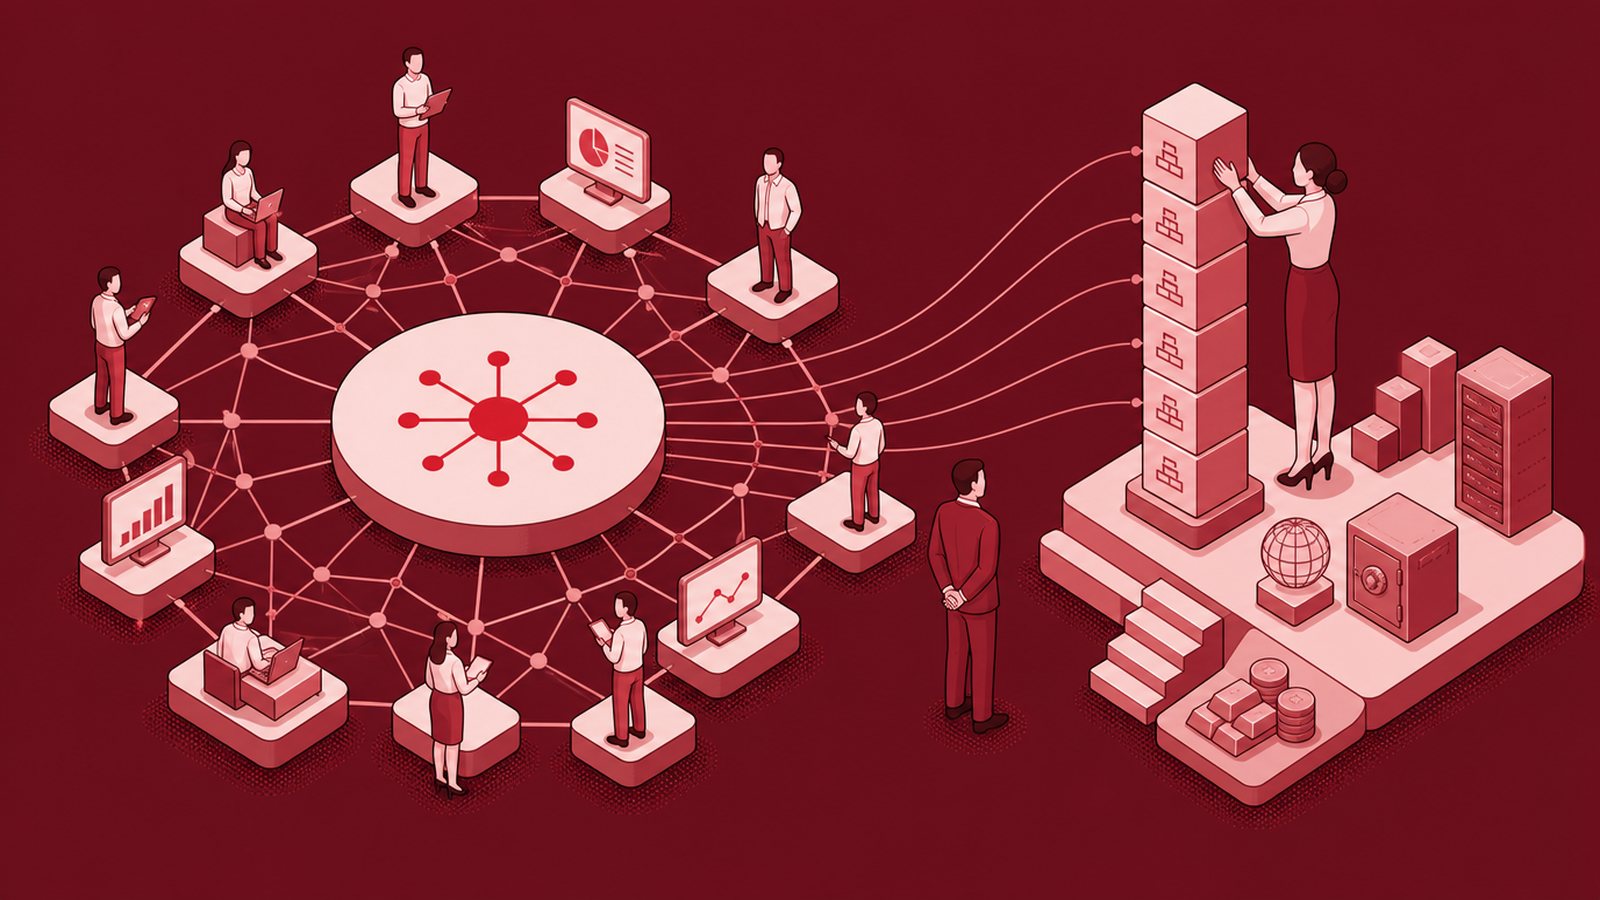
The term is used loosely, so let me be precise. A network effect exists when the value of a product to each user increases as more users join. That is a stricter condition than popularity, brand strength or scale economics, and most businesses described as having network effects do not.
There are several distinct varieties, and they differ in strength.
Direct or same side effects, where users benefit from other users of the same type. Messaging and social networks. These are the strongest and most defensible.
Cross side effects, where two distinct groups attract each other. Buyers and sellers on a marketplace, riders and drivers, merchants and cardholders. These are powerful but vulnerable, because either side can defect.
Data network effects, where usage generates data that improves the product, which attracts more usage. Strong in principle, though frequently overstated: many products reach diminishing returns on data far earlier than their advocates assume.
Liquidity effects, where the depth of a market itself is the product. Exchanges and marketplaces. These tend to be the most durable of all, because liquidity begets liquidity and fragmented liquidity serves nobody.
The critical structural consequence is that network effects produce winner takes most markets rather than competitive equilibria. Value concentrates in one or two participants per category, and the concentration is not accidental. It compounds.
The Accounting Problem
Here is the mechanism behind my decade of error.
Financial accounting was designed for an industrial economy in which value resided in factories, inventory and equipment. It records those faithfully. It has never adequately recorded intangible assets: user relationships, behavioural data, marketplace liquidity, brand, and the accumulated organisational knowledge of how to operate a platform.
The scale of the omission is now enormous. The World Intellectual Property Organization's 2026 report on global intangible investment found that investment in intangible assets has grown roughly three times faster than tangible investment since 2008, exceeding $10 trillion globally. It further found that intangible investment is more resilient, continuing to grow through periods of weak economic conditions when tangible investment contracts.
At the company level the effect is starker still. Analysis of several of the world's largest firms, including Apple, Nvidia, Costco, Eli Lilly and Mastercard, attributes approximately 98 percent of their market value to intangible assets, predominantly intellectual property related.
Consider what that means for a valuation framework anchored on book value. If 98 percent of a company's economic substance is invisible to the balance sheet, then price to book is not measuring what an investor thinks it is measuring. It is measuring almost nothing.
The Value Trap in Reverse
This produces a specific and dangerous inversion that I want to describe carefully, because it is counterintuitive.
Traditional value investing profits from mean reversion. Metrics such as price to book and price to sales tend to revert toward historical averages, so buying at low multiples and selling at high ones works over long periods.
Network effects break that mechanism. Companies with the strongest network effects tend to look most expensive on precisely these metrics, because their assets are unrecorded. And rather than reverting, their advantage compounds: strong networks attract more users, which strengthens the network, which attracts more users still. The strong get stronger and the weak get weaker.
The result is that a quantitative value screen will systematically avoid the businesses most likely to compound, and systematically favour businesses whose cheapness reflects genuine structural decline. Research suggests platforms with strong network effects can sustain valuations five to ten times higher than comparable businesses without them, and that discounted cash flow analysis routinely understates them because it cannot model the reflexive feedback loop.
I am not arguing that valuation discipline should be abandoned. I am arguing that it must be applied to a different set of measurements.
The Empirical Evidence of Concentration
If the theory is correct, we should observe extreme value concentration in categories with strong network effects. We do.
Alphabet, Amazon and Meta have been on track to capture close to 55 percent of global advertising spending outside China, and the growth of that group between the pandemic period and 2026 has been roughly five times faster than that of all other media owners combined.
That is not a market with a leader. That is a market with an oligopoly and a long tail of participants competing for the residual.
The behaviour of these companies confirms they understand the dynamic. Alphabet's acquisition of Wiz at around $32 billion, and the willingness of dominant platforms generally to pay substantial premiums, reflects a simple calculation: acquiring a leading platform simultaneously eliminates the most dangerous competitive threat and adds that platform's network to the acquirer's ecosystem. Premiums that appear irrational in isolation are rational when the asset being purchased is a compounding structural advantage.
What I Measure Instead
If accounting will not tell me what a network is worth, I have to measure network health directly. These are the indicators I rely on.
Growth in engaged participants, not registered accounts. Registration is a marketing outcome; engagement is a network outcome.
Interaction density. Transactions, matches or connections per active user per period. A network that is growing users while interaction density falls is diluting, not compounding.
Cross side balance. For two sided platforms, whether both sides are growing proportionally. Most marketplace failures I have examined were visible in advance as an imbalance between supply and demand growth.
Multi homing rates. The proportion of users who simultaneously use a competitor. Low multi homing indicates a genuine moat. High multi homing indicates a preference rather than a lock in, and preferences are cheap to change.
Unit economics at the margin. Whether the cost of acquiring the next participant is falling. In a true network effect it should, because existing participants do the recruiting.
Take rate trajectory. Whether the platform can raise its share of transaction value without losing participants. This is the clearest single test of whether pricing power actually exists.
When Network Effects Break
I have watched enough platforms decay to know these advantages are not permanent, and I think the current cycle carries a specific and underappreciated risk.
Multi homing erodes moats whenever switching costs fall. Standardised interfaces and portable identity have made switching cheaper across several categories.
Regulatory unbundling attacks the structure directly. Interoperability requirements, mandated data portability and restrictions on self preferencing are explicitly designed to convert network advantages into public infrastructure.
Demand side commoditisation occurs when the underlying service becomes generic and the network is no longer the reason for use.
And the risk I would highlight most strongly for the years ahead: agent mediated disintermediation. If artificial intelligence agents increasingly select products, services and suppliers on a user's behalf, the consumer facing network effect weakens considerably. A network built on human habit, familiarity and social presence is not obviously valuable to software that evaluates options on price and specification without loyalty. I do not know how this resolves. I do know that any platform thesis constructed today should be stress tested against it.
The Portfolio Construction Consequence
This is where the analysis becomes practical, and where most investors quietly fail.
If network effects produce winner takes most outcomes, then a market capitalisation weighted index will become progressively more concentrated, and that concentration is a feature of the underlying economics rather than a distortion to be corrected. Investors who mechanically diversify away from concentration in such a market are, in effect, betting against the dominant economic structure of their era.
But holding concentrated positions in a small number of platforms creates genuine and non trivial risk: regulatory action, technological displacement, and the correlated drawdowns that follow when a crowded consensus reverses.
My working resolution is as follows.
Hold platform exposure deliberately rather than incidentally. Know what proportion of the portfolio depends on network effects, across every fund and every direct holding. Most investors I meet are far more concentrated than they believe, because the same names appear in multiple vehicles.
Rebalance on network health, not on price. Trimming a compounding network because it has appreciated is precisely the mechanism that destroys returns in power law markets. I trim when interaction density falls, when multi homing rises, or when take rate becomes contested, not when the share price rises.
Diversify by network type, not merely by sector. A payments network, an exchange, a marketplace and a social platform face genuinely different regulatory and technological risks, even though a sector classification places several of them together.
Look beyond the obvious geography. Some of the most attractive network businesses I have examined recently operate regionally rather than globally: payments and commerce platforms in India, Southeast Asia, Latin America and Africa, where a local network effect has already reached escape velocity within its market and where valuations do not yet reflect it.
Applying the Framework: A Worked Illustration
Let me make this concrete, using a generic example rather than a specific company so that the method rather than the conclusion is what carries.
Suppose two businesses appear in the same screen. Both trade at high multiples of book value. Both have grown revenue at similar rates. A conventional value framework rejects both.
The first is a food delivery marketplace. Applying my measurements: cross side network, moderate liquidity effect within dense urban geographies, high multi homing (most customers hold three competing applications and most couriers work for two), take rate contested by both restaurants and regulators, and customer acquisition cost that has not fallen with scale because loyalty is transactional. My assessment is that this business has scale economics and brand, but its network effect is weak and localised. The high multiple is not supported by an unrecorded asset. It is supported by hope.
The second is a national payments network. Direct and cross side effects reinforcing each other, near universal merchant acceptance, extremely low multi homing at the infrastructure layer, take rate stable across decades, and marginal cost of an additional transaction approaching zero. Here the high multiple reflects an enormous unrecorded asset: acceptance infrastructure that a competitor could not rebuild at any price, because the difficulty is coordination rather than capital.
Same screen. Same rejection under conventional analysis. Entirely different businesses. The framework is what separates them, and separating them is where the return lives.
Closing Thought
The intangible economy is not arriving. It arrived, and our measurement conventions did not follow.
An investor who continues to assess businesses primarily through the assets recorded on their balance sheets is using an instrument calibrated for a world that no longer describes where value is created. The correction is not to abandon rigour. It is to redirect it toward the things that actually compound: participants, interactions, liquidity and pricing power.
Learn to measure the network, and a substantial portion of the modern market becomes legible. Refuse to, and it will continue to look expensive right up until the moment it looks unreachable.
Sources and further reading (9)
- Platform business models and network effects, TMT Investment Banking Guide
- The platform economy, network effects and valuation, Sparkline Capital
- World intangible investment highlights 2026, WIPO analysis, The Intangible Economy
- Intangible assets as a share of market value in leading companies, IPWatchdog
- The platform business model and network effects at scale, FourWeekMBA
- Types of platform business models, 2026 guide, FourWeekMBA
- The impact of intangible assets on the market value of companies, cross sector evidence, MDPI Mathematics
- The impact of platform business models on the valuations of unicorn companies, ScienceDirect
- Platform economy overview and market concentration debate, Wikipedia